Open Banking, Made
Understandable
Open Banking, Made
Understandable
Open Banking, Made
Understandable
India built a national system that lets people share their financial data with a lender or insurer in minutes instead of days. But nearly half of users were quitting before they finished. I redesigned the consent journey around trust and clarity, cutting mid-journey drop-off from 40% to 5%, on a platform serving ~70% of India's insurance ecosystem.
India built a national system that lets people share their financial data with a lender or insurer in minutes instead of days. But nearly half of users were quitting before they finished. I redesigned the consent journey around trust and clarity, cutting mid-journey drop-off from 40% to 5%, on a platform serving ~70% of India's insurance ecosystem.
India built a national system that lets people share their financial data with a lender or insurer in minutes instead of days. But nearly half of users were quitting before they finished. I redesigned the consent journey around trust and clarity, cutting mid-journey drop-off from 40% to 5%, on a platform serving ~70% of India's insurance ecosystem.
Drop-off
40% → 5% mid-journey
40% → 5% mid-journey
Reach
~70% of India's insurance ecosystem
~70% of India's insurance ecosystem
Scale
5.5Cr+ users on the platform
5.5Cr+ users on the platform
Recognition
3× SamvAAd awards
3× SamvAAd awards
Role
Senior UX Designer
Senior UX Designer
Senior UX Designer
Company
Finarkein Analytics
Finarkein Analytics
Finarkein Analytics
TEAM
Led a cross-functional design team of 5
Led a cross-functional design team of 5
Led a cross-functional design team of 5
Duration
2022 to 2024
2022 to 2024
2022 to 2024
Scope
Consumer consent journey, consent dashboard, admin consoles for banks and lenders, design standards
Consumer consent journey, consent dashboard, admin consoles for banks and lenders, design standards
Consumer consent journey, consent dashboard, admin consoles for banks and lenders, design standards

Login.
Link.
Consent.
Login. Link. Consent.
No PDFs. No bank visits. No guesswork.
No PDFs. No bank visits. No guesswork.


Login.
Link.
Consent.
No PDFs. No bank visits. No guesswork.
My Role
My Role
Consent architecture.
Consent architecture.
What, why, who, and how long, in plain language
What, why, who, and how long, in plain language
What, why, who, and how long, in plain language
System mapping
System mapping
The full ecosystem, before a single screen
The full ecosystem, before a single screen
The full ecosystem, before a single screen
Diagnosis and iteration
Diagnosis and iteration
Found where users quit; led three redesigns
Found where users quit; led three redesigns
Found where users quit; led three redesigns
Designing for failure
Designing for failure
20+ failure paths, no dead ends
20+ failure paths, no dead ends
20+ failure paths, no dead ends
Back-stage tools
Back-stage tools
Admin consoles for banks and lenders
Admin consoles for banks and lenders
Admin consoles for banks and lenders
Team and standards
Team and standards
Led a team of 5; kept every surface consistent
Led a team of 5; kept every surface consistent
Led a team of 5; kept every surface consistent
The Problem
The Problem
tHE Context
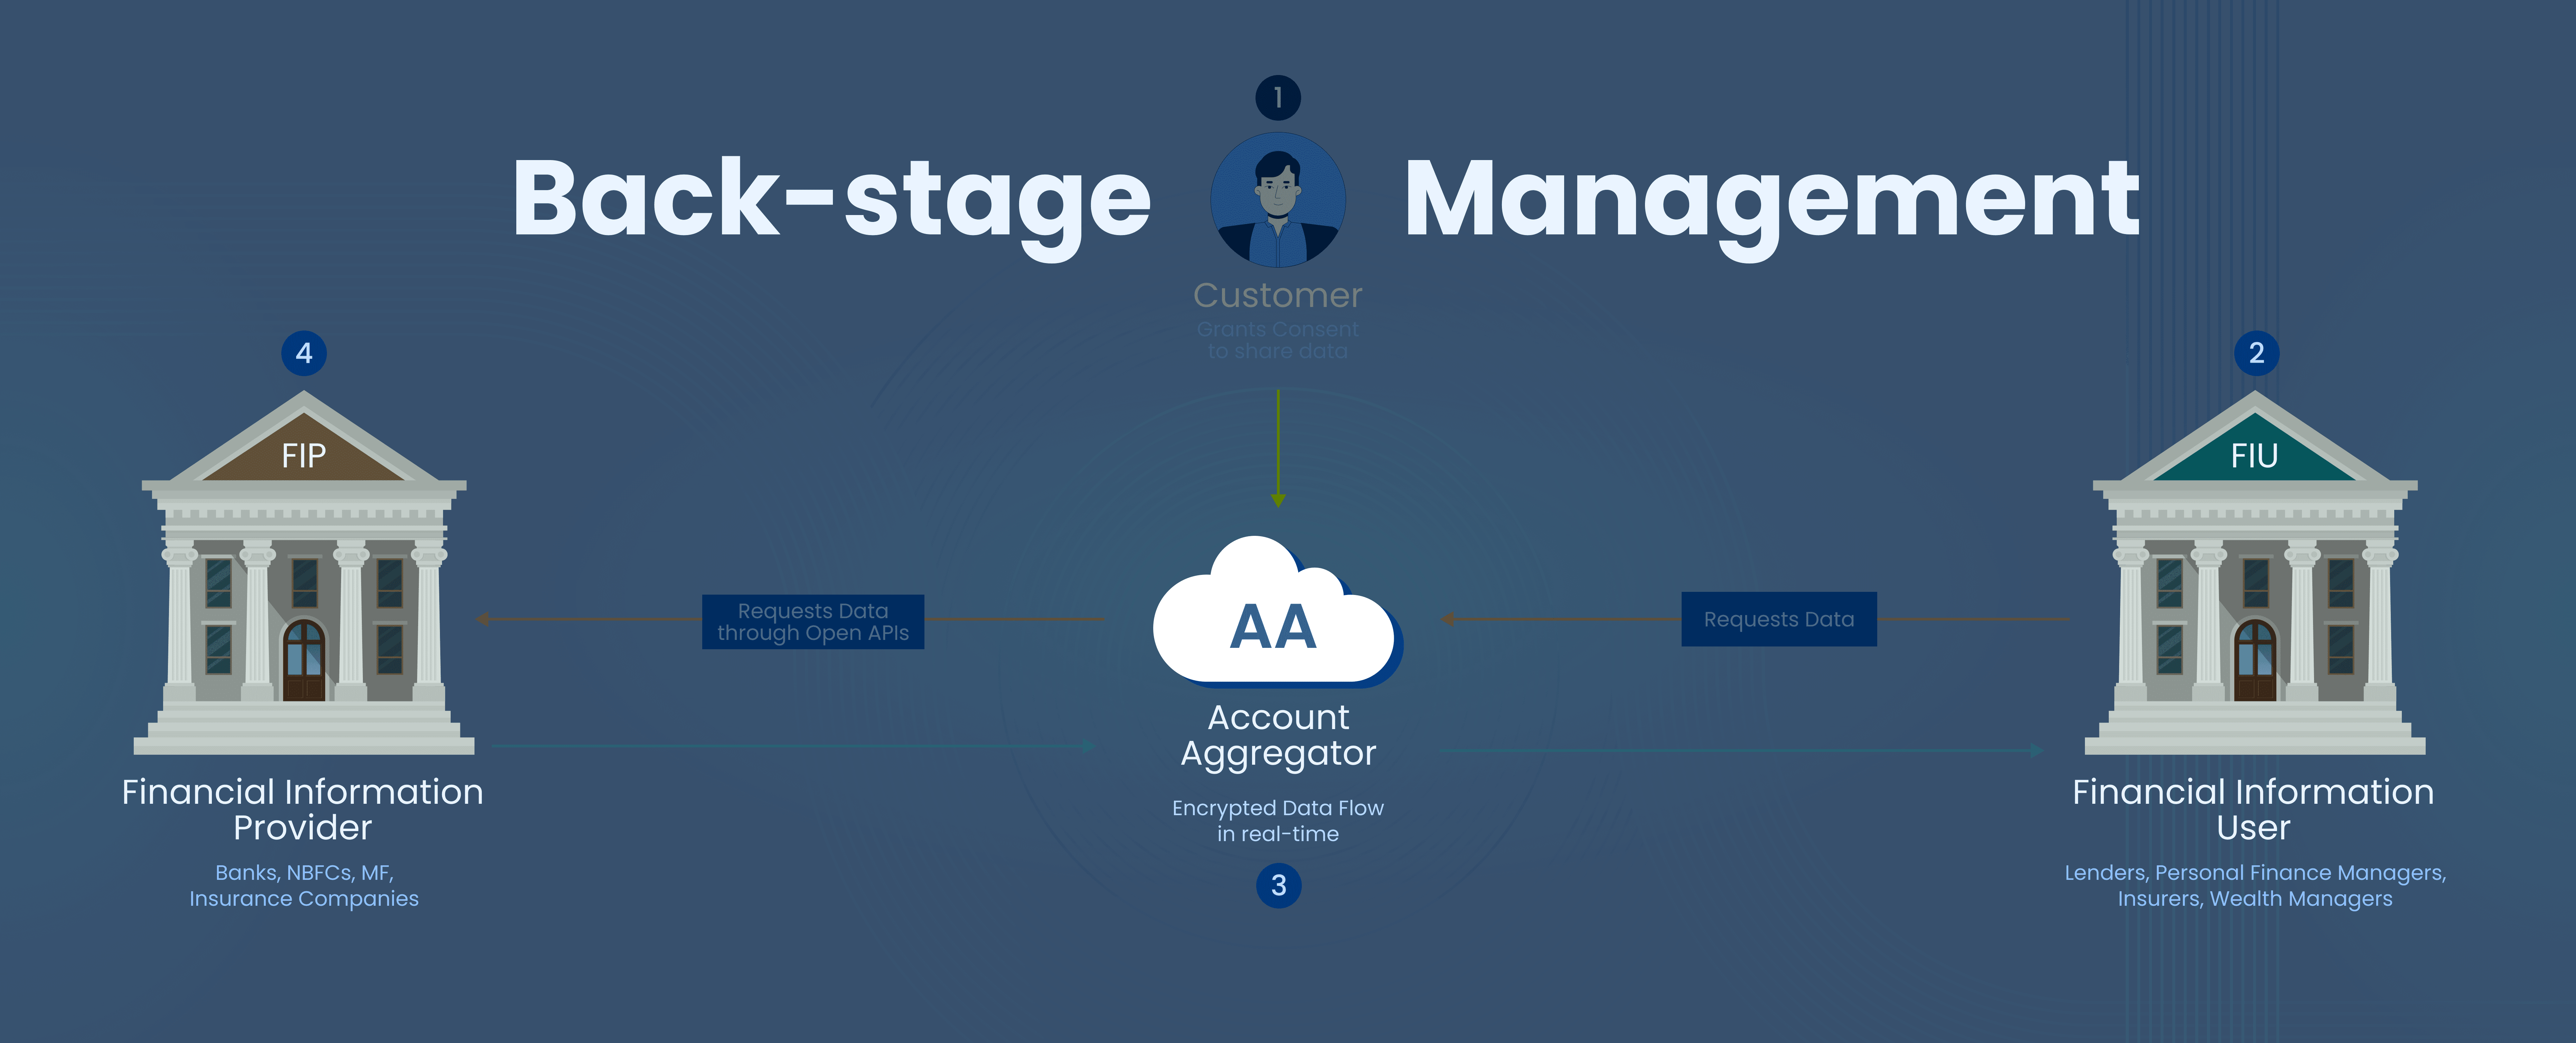
Think of it as open banking, built as national infrastructure. India's Account Aggregator (AA) network lets a person share financial data, like bank statements, from the institutions that hold it (banks, insurers) with the ones that need it (lenders, insurers), only with their explicit consent. The AA sits in the middle and never sees the data. It only manages consent.
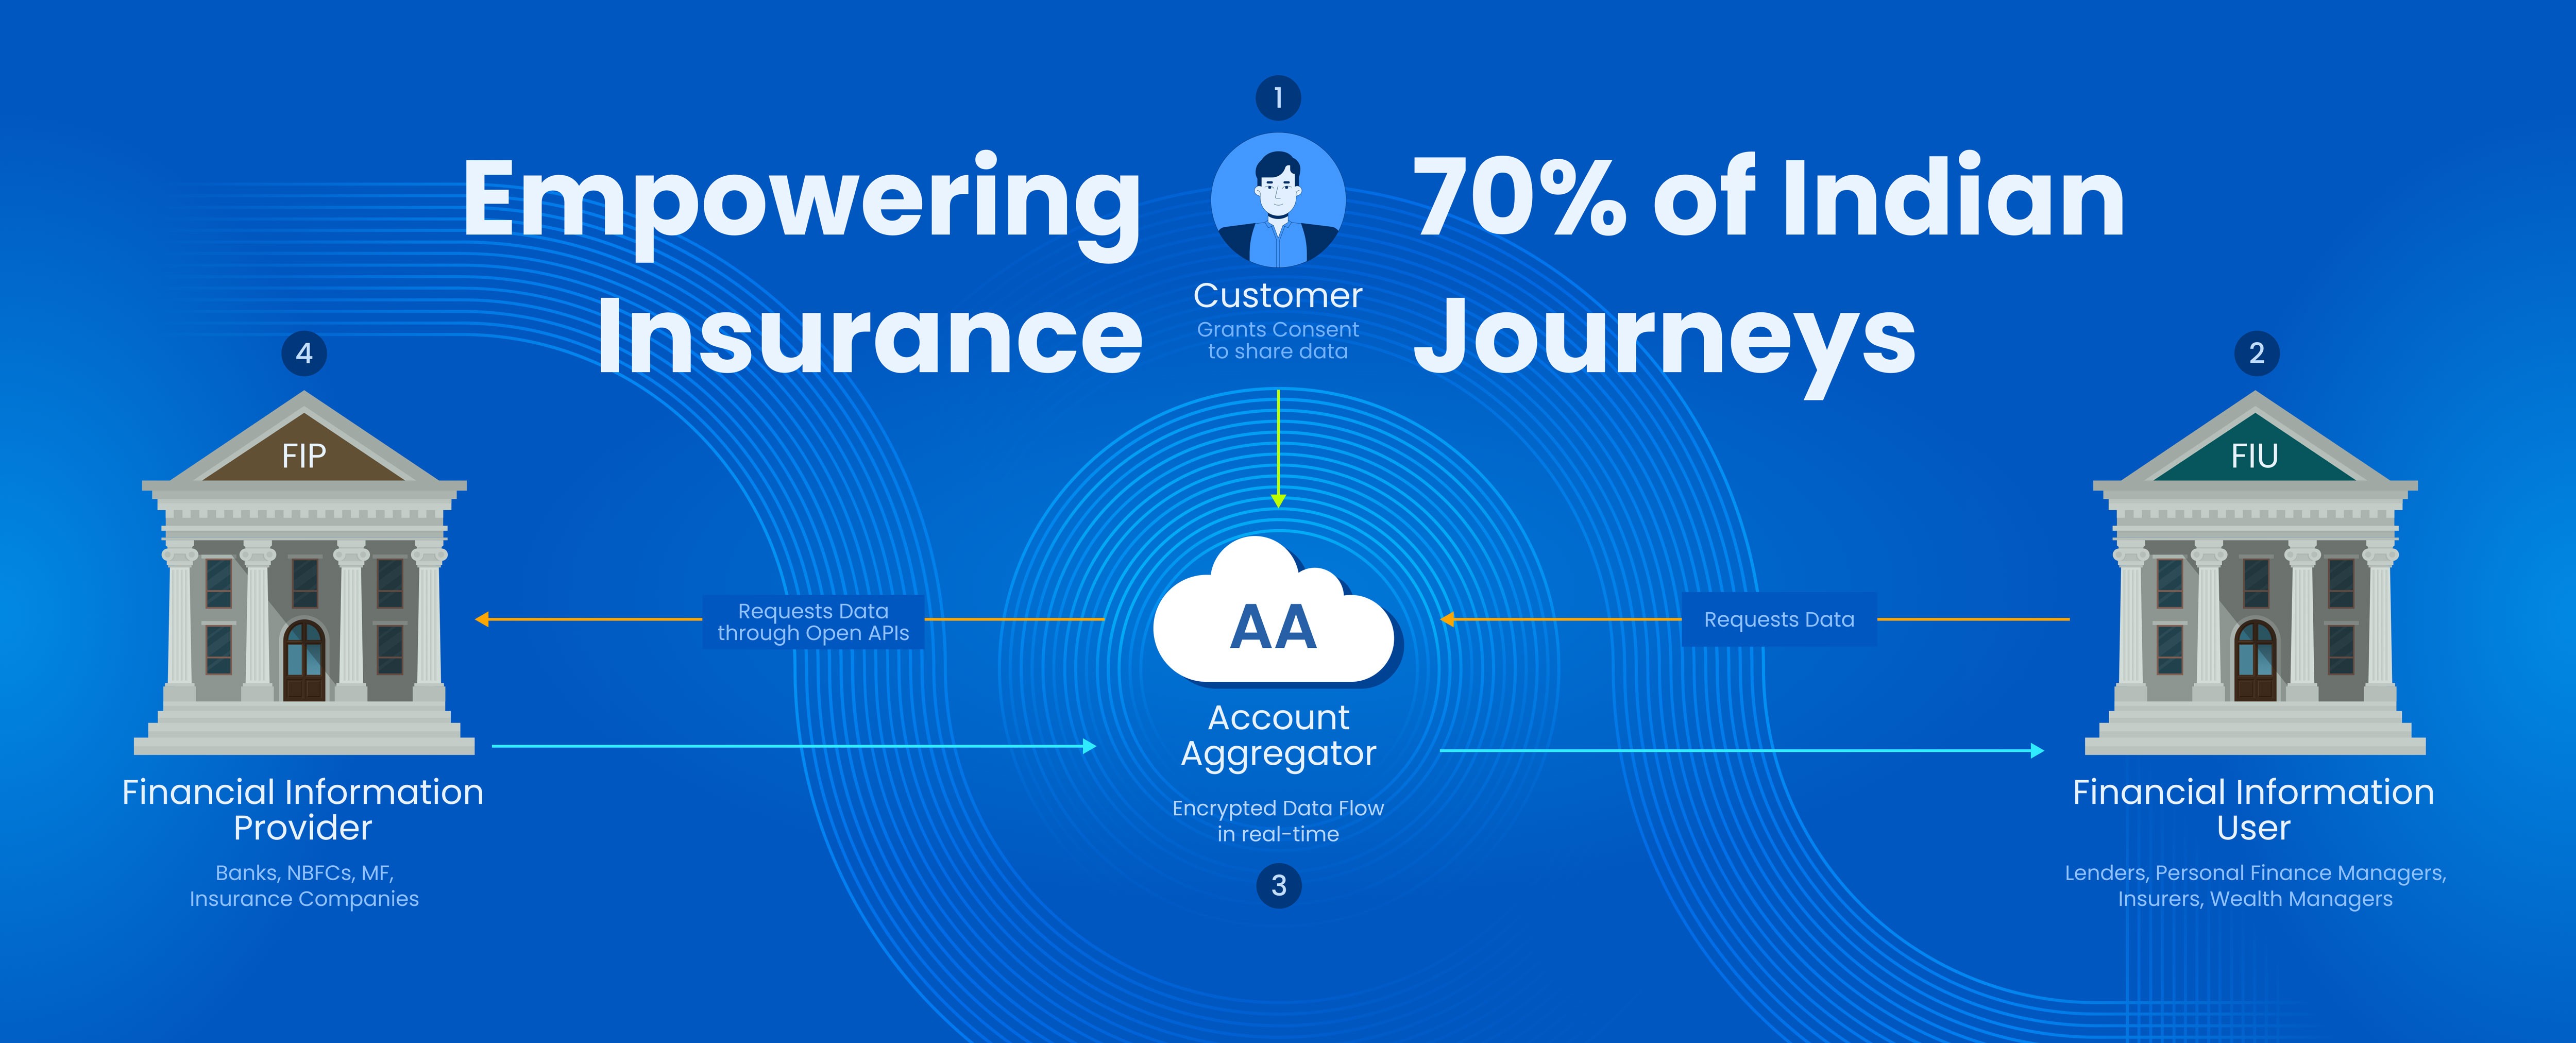
Banks hold the data, lenders request it, and the Account Aggregator manages consent without ever seeing the data.
tHE Context
Think of it as open banking, built as national infrastructure. India's Account Aggregator (AA) network lets a person share financial data, like bank statements, from the institutions that hold it (banks, insurers) with the ones that need it (lenders, insurers), only with their explicit consent. The AA sits in the middle and never sees the data. It only manages consent.
~3 working days
Manual Process
Manual Process
Under 3 minutes
The AA Flow
The AA Flow
The framework made it fast.
The problem was getting people to finish
40% of Users Quit Halfway
Consent was buried in fine print, and people were asked to make technical choices, like picking an "AA handle," with no idea what they meant.
Consent was buried in fine print, and people were asked to make technical choices, like picking an "AA handle," with no idea what they meant.
Meet Rishi, 27, freelance design consultant in Bangalore, with income spread across several bank accounts. He wants health insurance, and every confusing screen or delayed OTP is one more reason to give up. We'll follow him through the journey.

Rishi
Rishi
Rishi
The Digitally Native Freelancer
The Digitally Native Freelancer
AGE
AGE
27
27
LOCATION
LOCATION
Bangalore, India
Bangalore, India
Occupation
Occupation
Independent Design Consultant
Independent Design Consultant
Bio
Bio
Rishi has been freelancing for three years. While his income is high, it is irregular and spread across multiple bank accounts. He is currently looking to buy a comprehensive health insurance policy but is frustrated by the manual "proof of income" process required by traditional insurers.
Rishi has been freelancing for three years. While his income is high, it is irregular and spread across multiple bank accounts. He is currently looking to buy a comprehensive health insurance policy but is frustrated by the manual "proof of income" process required by traditional insurers.
Goals & Motivations
Goals & Motivations
He seeks instant financial mobility through a secure, one-click digital consent flow that replaces manual bank visits and physical paperwork. He aims to verify his financial history to "unlock" insurance services while maintaining total credential privacy.
He seeks instant financial mobility through a secure, one-click digital consent flow that replaces manual bank visits and physical paperwork. He aims to verify his financial history to "unlock" insurance services while maintaining total credential privacy.
Critical Pain Points
Critical Pain Points
The manual friction of downloading and managing PDF bank statements often leads Rishi to abandon service journeys due to sheer exhaustion. He lacks transparency regarding how his data is stored by third parties and faces significant frustration when technical hurdles, like delayed OTPs, disrupt his progress.
The manual friction of downloading and managing PDF bank statements often leads Rishi to abandon service journeys due to sheer exhaustion. He lacks transparency regarding how his data is stored by third parties and faces significant frustration when technical hurdles, like delayed OTPs, disrupt his progress.
The Diagnosis
The Diagnosis
01
01
What we needed to know
What we needed to know
How does a legal data handshake work?
How does a legal data handshake work?
Method
Method
Ecosystem and event-sequence mapping
Ecosystem and event-sequence mapping
What we learned
What we learned
Consent should only appear after identity and accounts are verified, and it must answer four questions: what, why, who, and how long.
Consent should only appear after identity and accounts are verified, and it must answer four questions: what, why, who, and how long.

02
02
What we needed to know
What we needed to know
Where and why do users quit?
Where and why do users quit?
Method
Method
Audit of the live consent journey
Audit of the live consent journey
What we learned
What we learned
The flow wasn't too slow, it felt uncertain. An oversimplified graphic set the wrong expectations, and the AA handle choice stalled people at step one.


Rishi, before: asked to pick an "AA handle" on screen one. He has no idea what it is, so he closes the app.
03
03
What we needed to know
What we needed to know
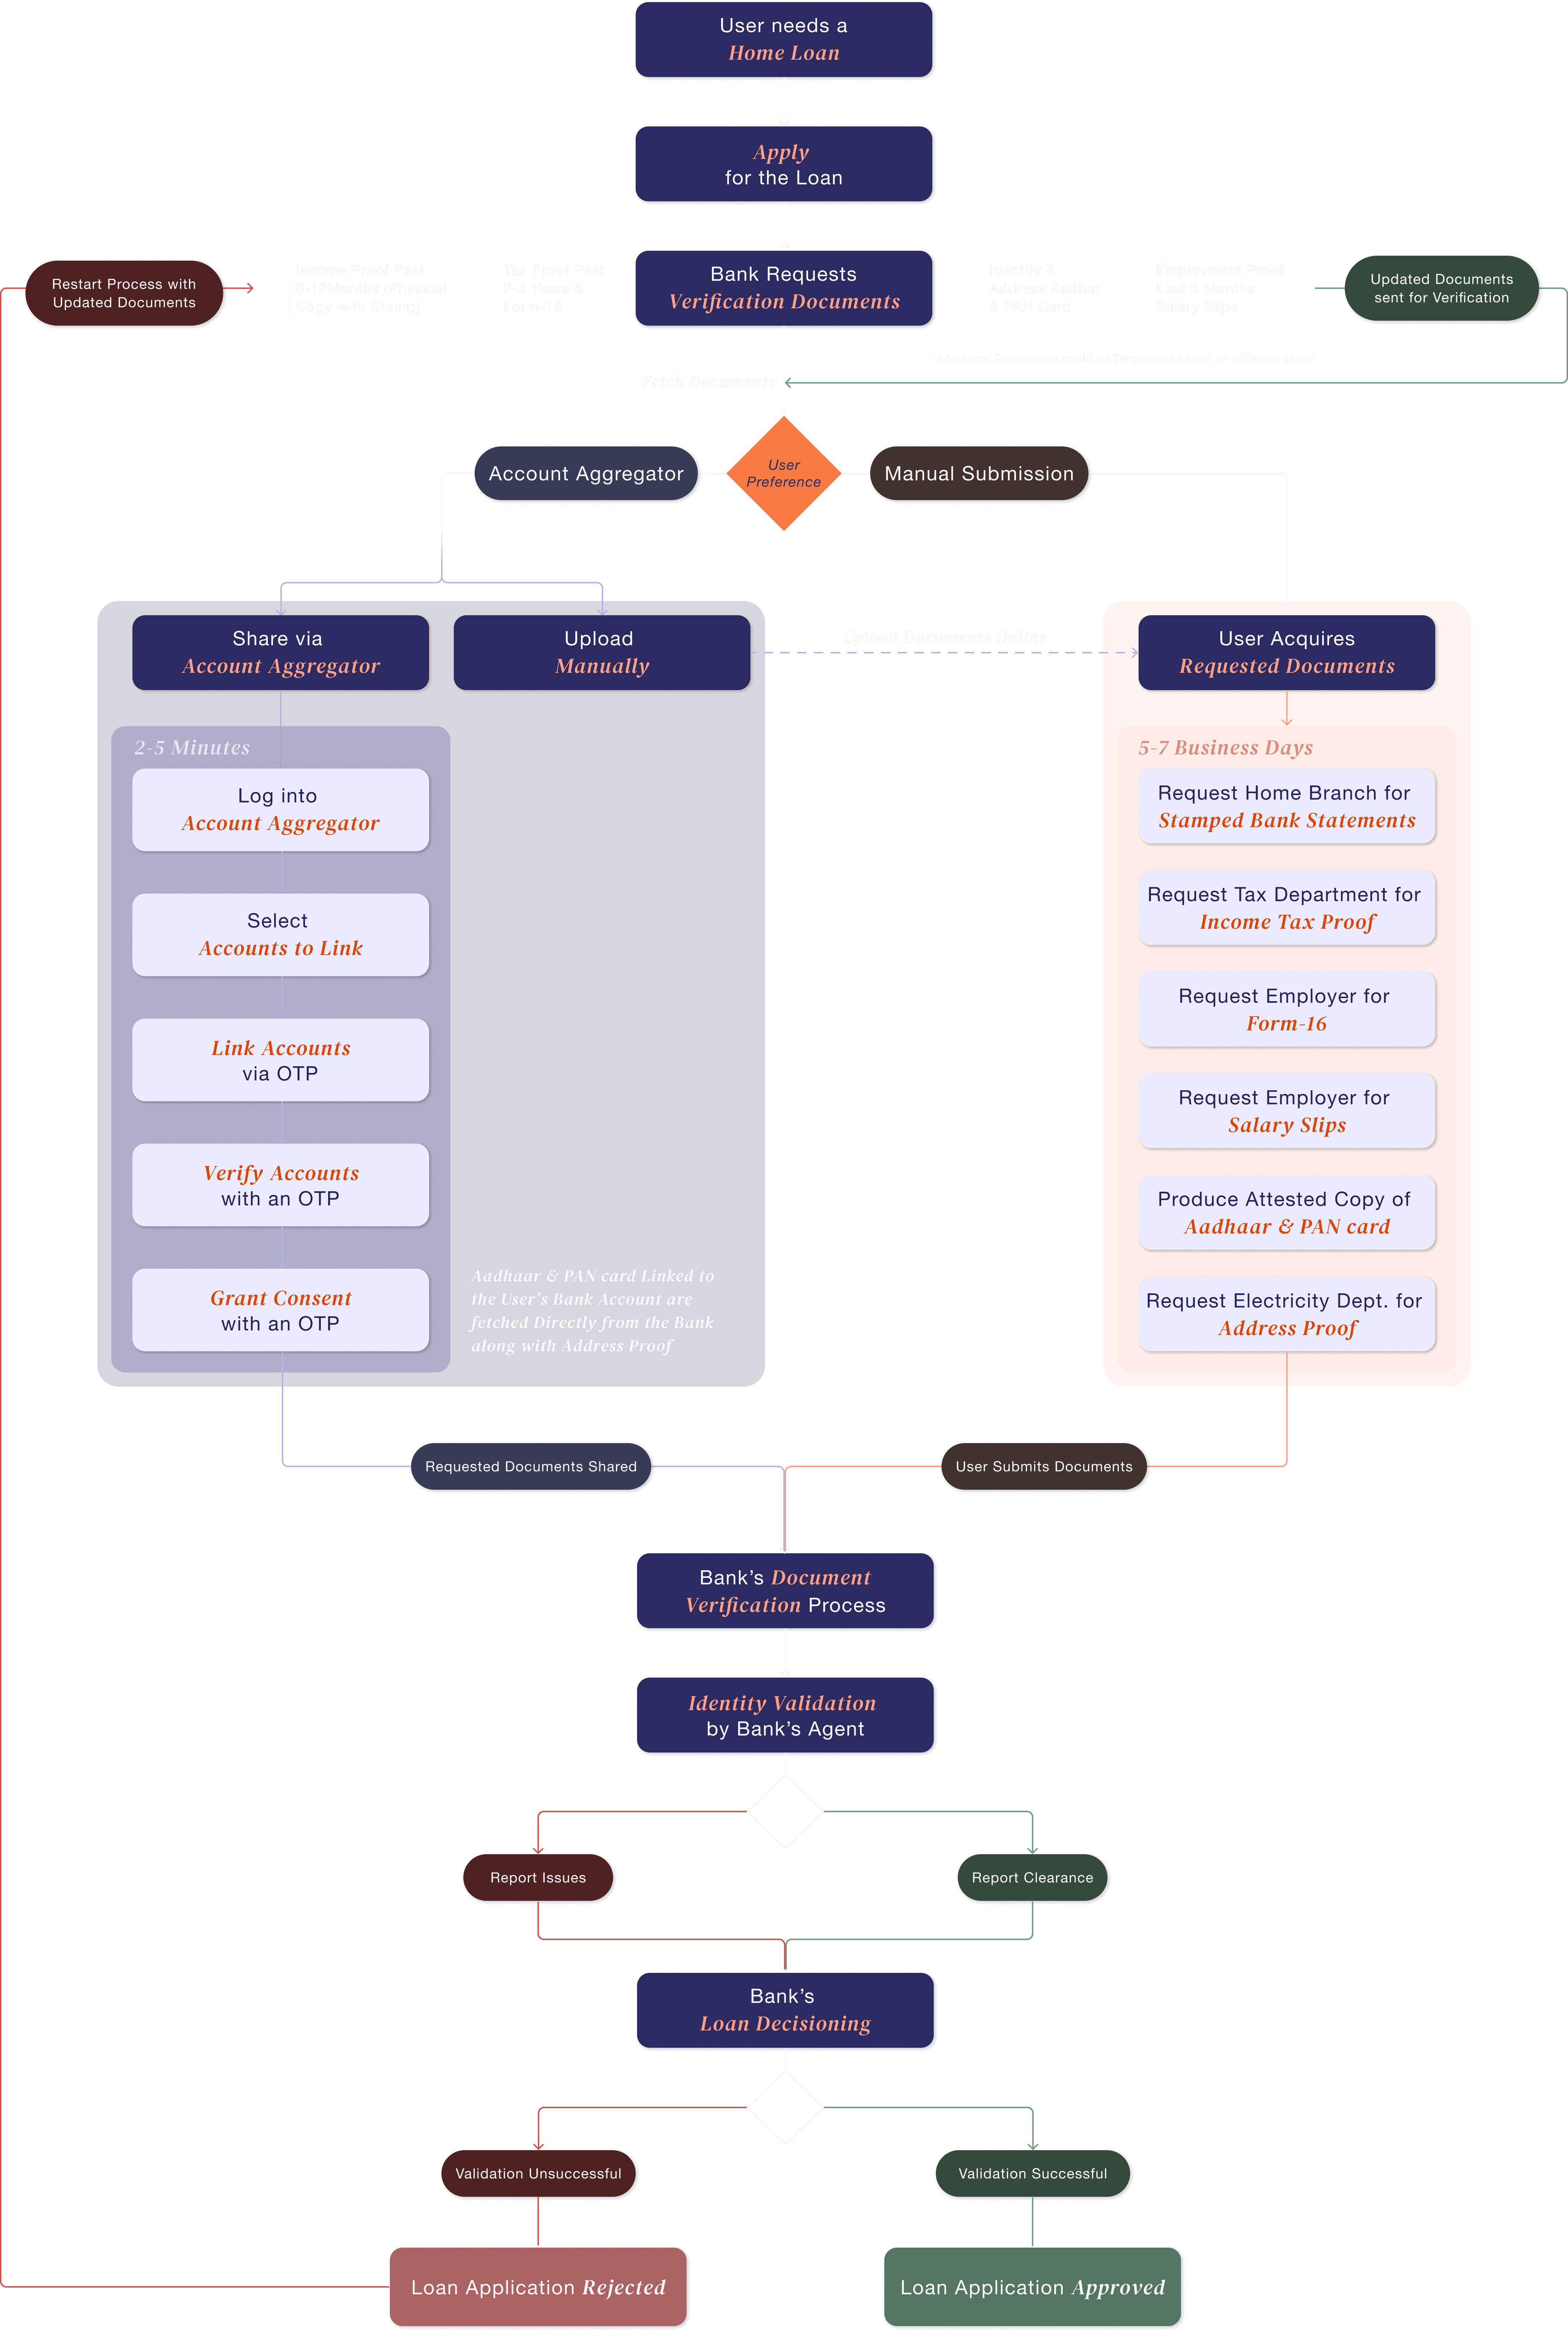
What happens when something breaks?
What happens when something breaks?
Method
Method
Mapped 20+ failure scenarios
Mapped 20+ failure scenarios
What we learned
What we learned
Bank timeouts, mismatched mobile numbers, and partial fetches are inevitable. The design had to make sure no one got stranded.
Bank timeouts, mismatched mobile numbers, and partial fetches are inevitable. The design had to make sure no one got stranded.
Rishi, after: one of his banks still has his old number. He updates it and re-verifies, without starting over.
Three Rounds of Redesign
Three Rounds of Redesign
Phase 1 - Analyzing the Friction : Theory vs. Reality
The Challenge: The journey felt like a "Black Box." Consent was hidden in fine print, and users were forced to make technical choices (like selecting an AA handle) without any context.
Login
Select Accounts to Link
Link Accounts via OTP
Grant Consent
Consent Status

Dense text forced users to rely on an oversimplified graphic. This created an expectation gap and frustration when the actual journey felt much longer.
Forcing a technical "AA handle" choice without context introduced immediate friction. This blind decision created uncertainty that stalled the flow at the very first step.
Login
Select Accounts to Link
Link Accounts via OTP
Grant Consent
Consent Status
Dense text forced users to rely on an oversimplified graphic. This created an expectation gap and frustration when the actual journey felt much longer.
Forcing a technical "AA handle" choice without context introduced immediate friction. This blind decision created uncertainty that stalled the flow at the very first step.
Consent hidden, choices blind.
Pivot: link one account at a time.
Phase 2 - The Modular Shift : Scaling Complexity
The Challenge: As the ecosystem expanded to Insurance, GST, and Mutual Funds, the screen became an information graveyard.
Select FIP(s)
Login
Select Accounts to Link
Link Accounts via OTP
Grant Consent
Consent Status

Identifying the user's FIPs upfront gave the system the data needed to pre-select the correct AA handle. This transformed a confusing manual choice into a predictive, invisible step, clearing the path for a frictionless login.
New data types crowded the screen.
Pivot: ask for the bank first, so the AA handle is picked automatically.
Phase 3 - The "Zero-Friction" Flow : The Latest Iteration
The Challenge: Even with a better UI, the journey felt too long. We needed to remove every unnecessary step.
Login
Link Accounts via OTP
Grant Consent
Consent Status

We made the process easier by picking the accounts automatically and showing the rules clearly from the start. This took the guesswork out of the journey, making users feel in control instead of confused.
Still too long.
Pivot: consent terms on screen one; accounts fetched for the user.
Rishi, after: he sees what's shared, why, and for how long, then logs in, links, and consents. Under 3 minutes, insurance application done.
From finding to feature
From finding to feature
Research told us what was broken. This is what we built because of it.
Research told us what was broken. This is what we built because of it.
Trust
CONSENT HIDDEN IN FINE PRINT
The 4 W's, shown on screen one
NO RECORD OF WHAT YOU AGREED TO
Consent and transaction IDs shown at the end
Effort
BLIND TECHNICAL CHOICES
AA handle picked from your bank
TOO MANY STEPS
Three decisions: login, link, consent
Resilience
BANK AND SMS FAILURES
A manual upload fallback
WRONG NUMBER ON FILE
Fix it without starting over
Control
ANXIETY AFTER SAYING YES
Track, pause, and revoke consent
CONSENTS QUIETLY EXPIRE
One-tap relinking
The Solution
The Solution
A front stage people trust, and a back stage institutions can run.
A front stage people trust, and a back stage institutions can run.
Information Architecture
One journey to give consent, one dashboard to manage it.
One journey to give consent, one dashboard to manage it.
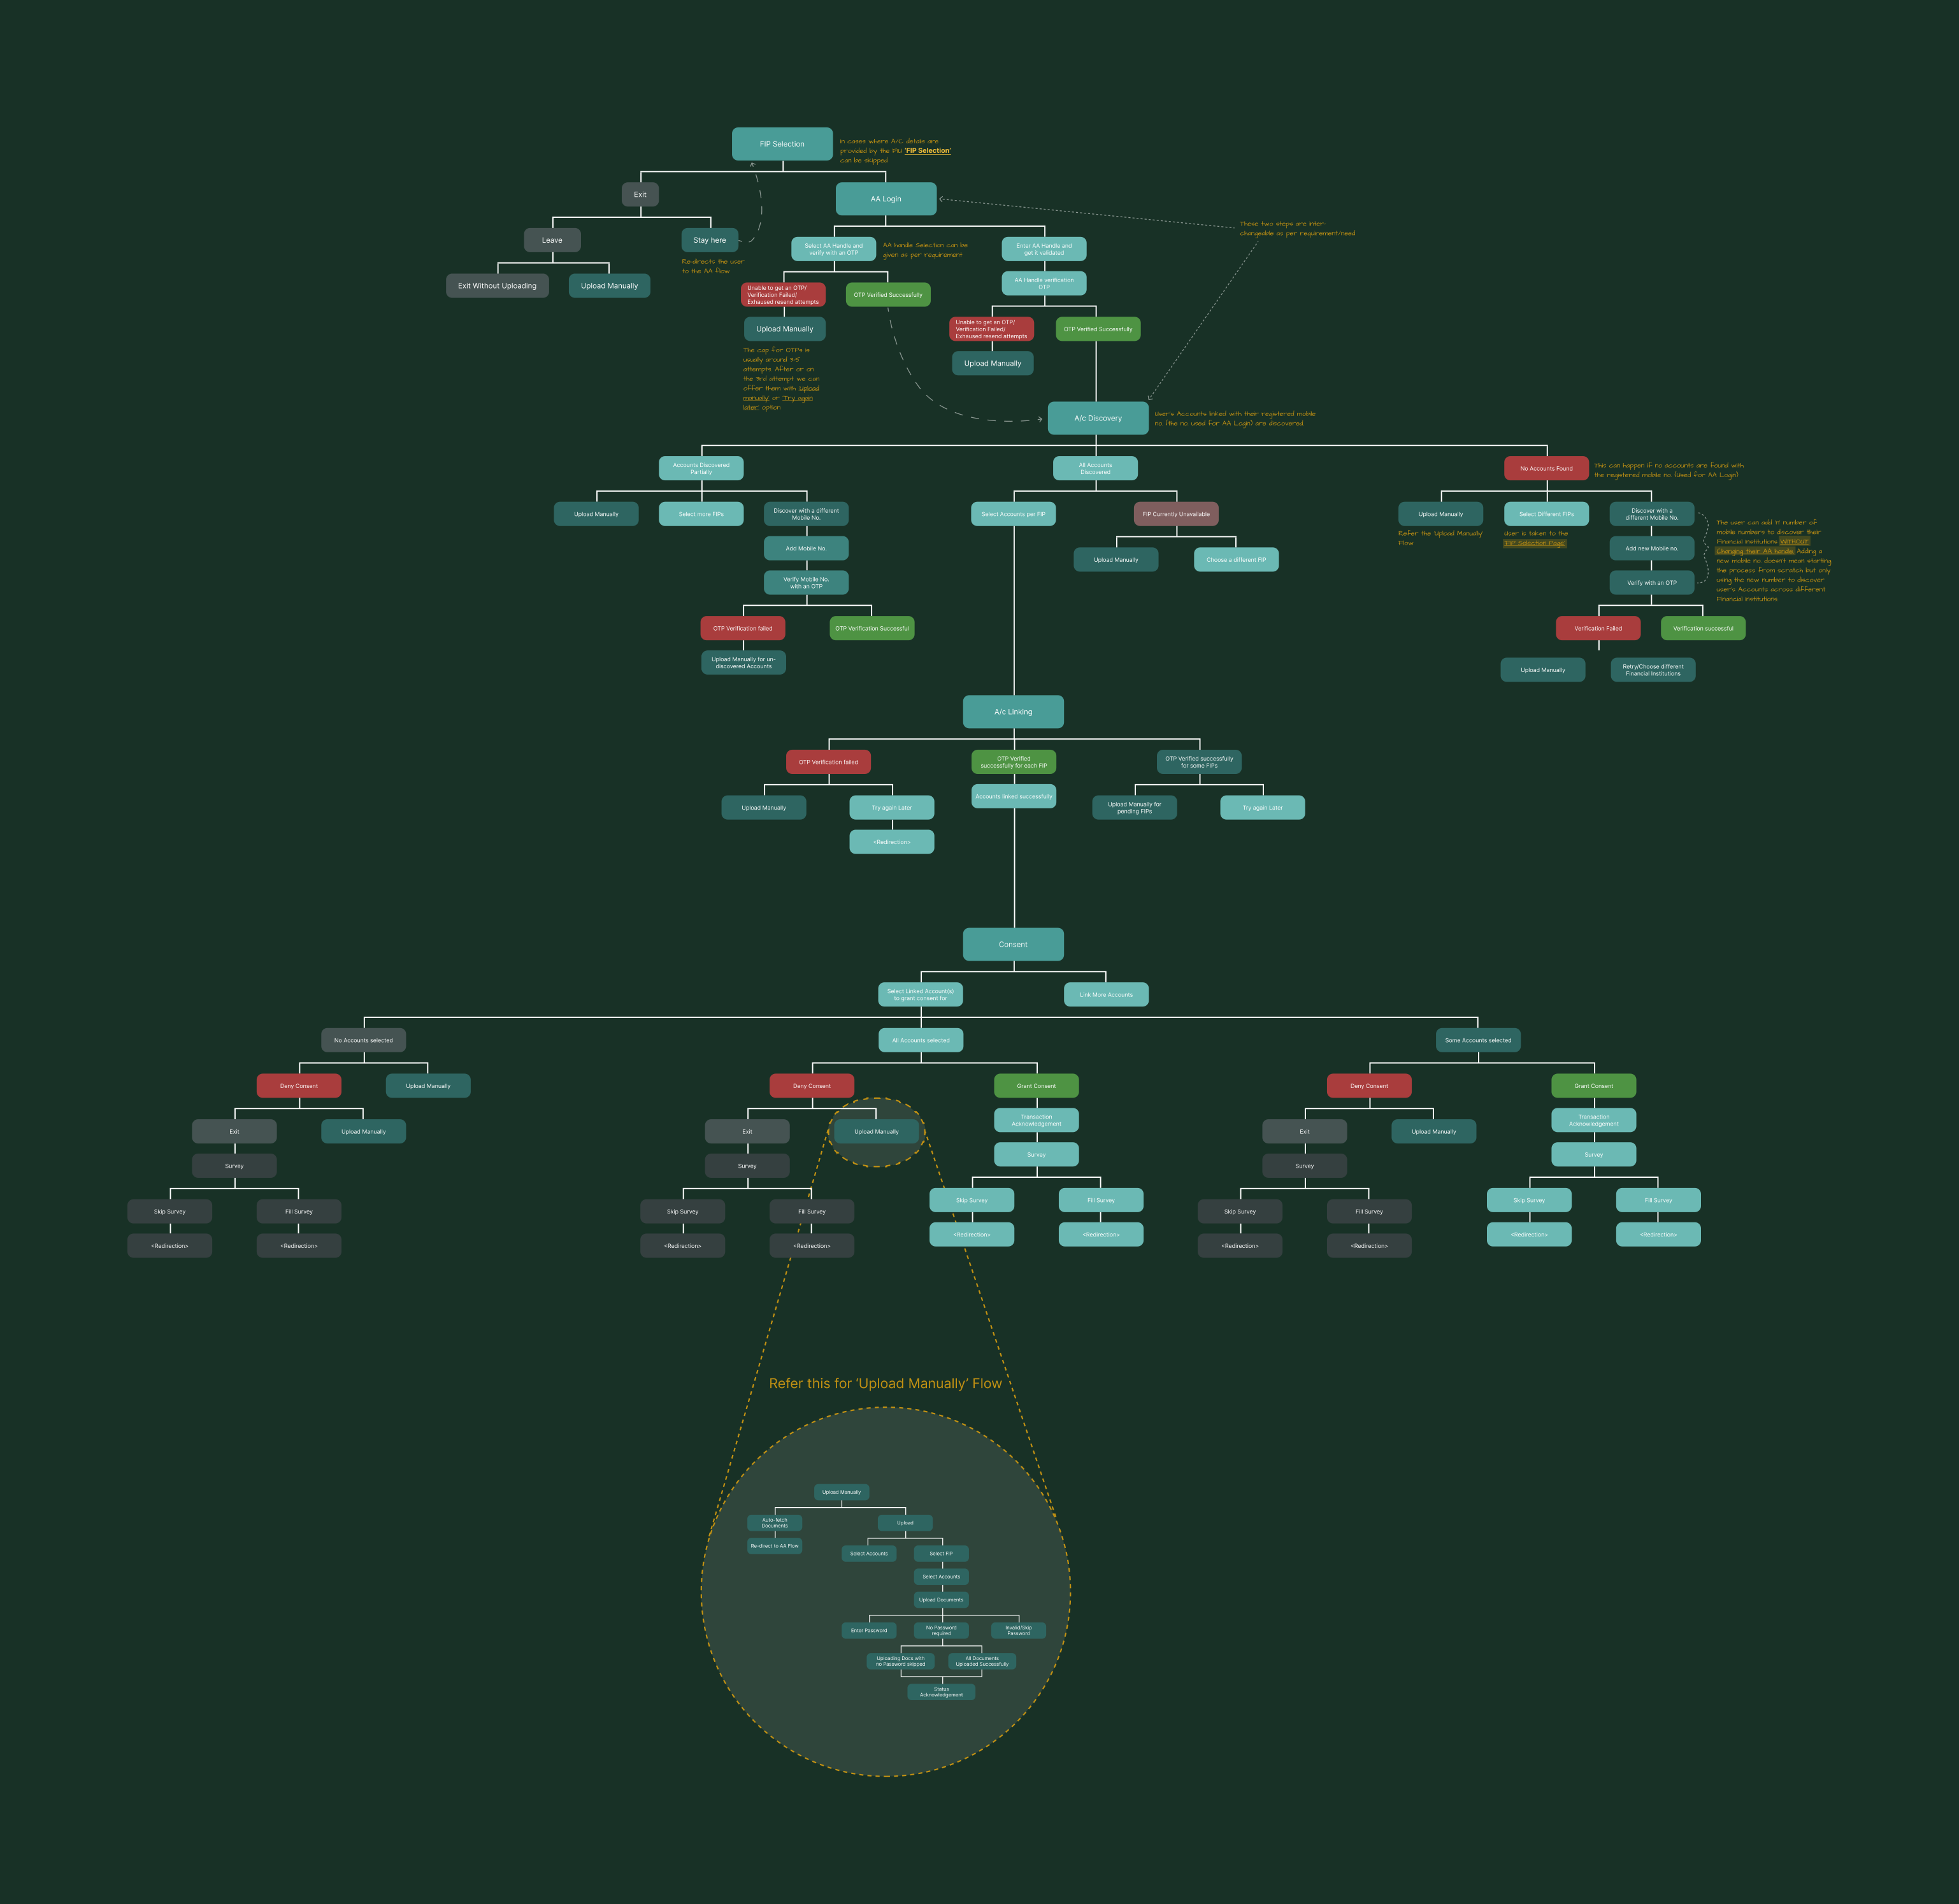
The consent journey
Discover, link, review, consent, with fallbacks when something fails.
Discover, link, review, consent, with fallbacks when something fails.
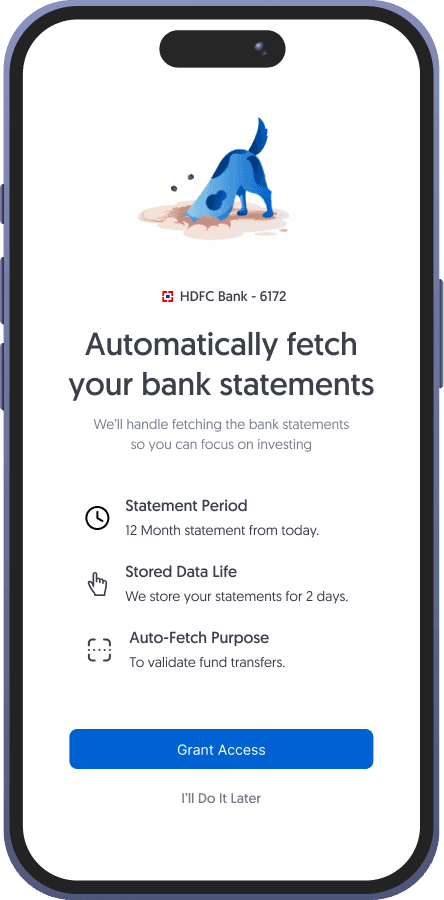
Establishing a secure handoff from the third-party FIU portal to the Account Aggregator’s consent environment.
Establishing a secure handoff from the third-party FIU portal to the Account Aggregator’s consent environment.
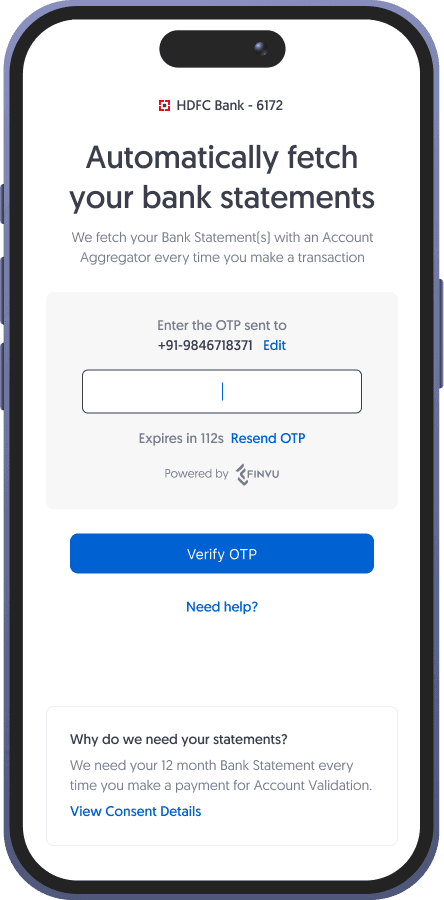
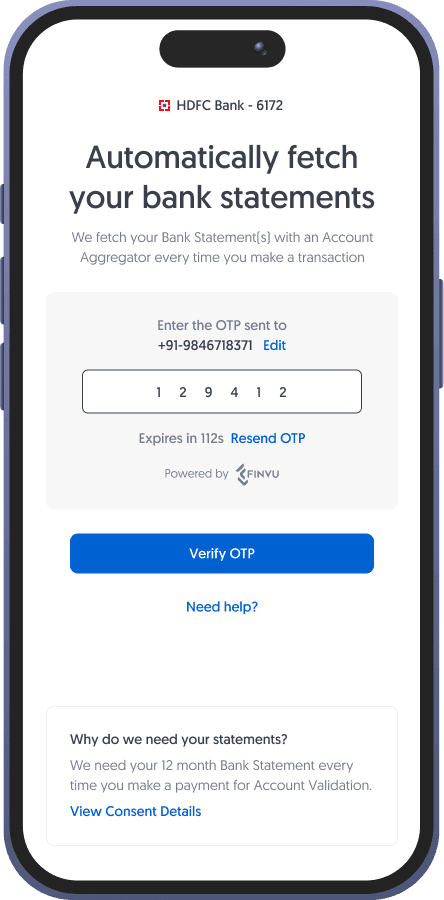
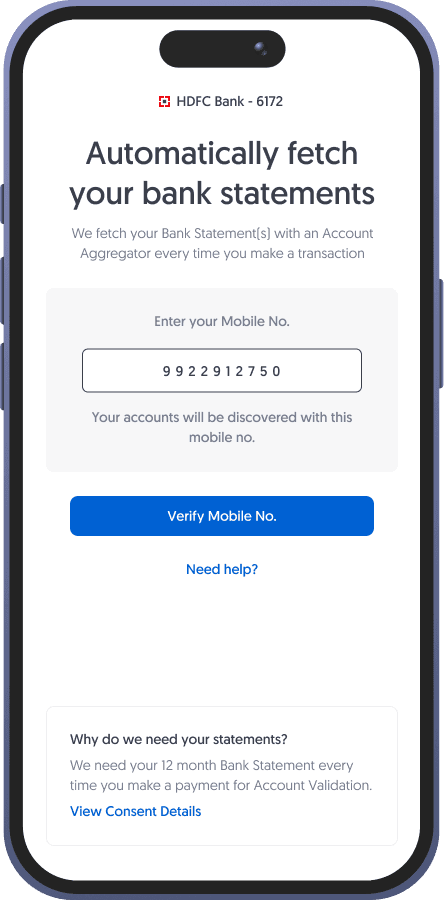
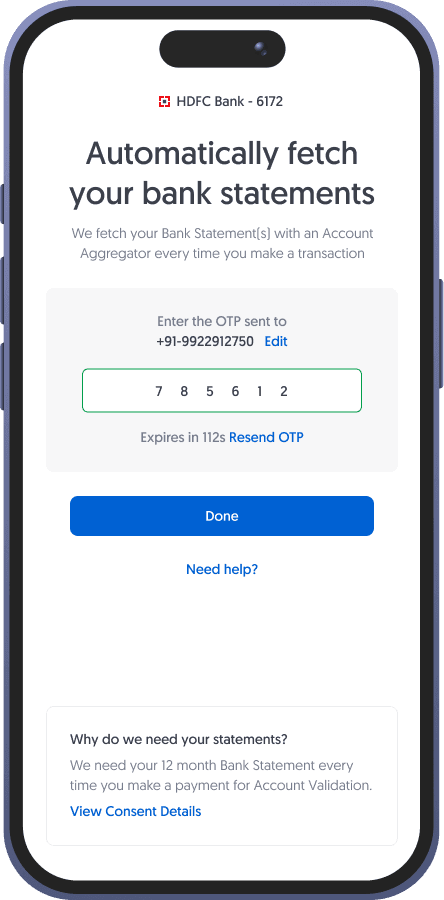
Utilizing masked identifiers and OTP-based verification to ensure the user is securely linked to the correct financial profile.
Utilizing masked identifiers and OTP-based verification to ensure the user is securely linked to the correct financial profile.
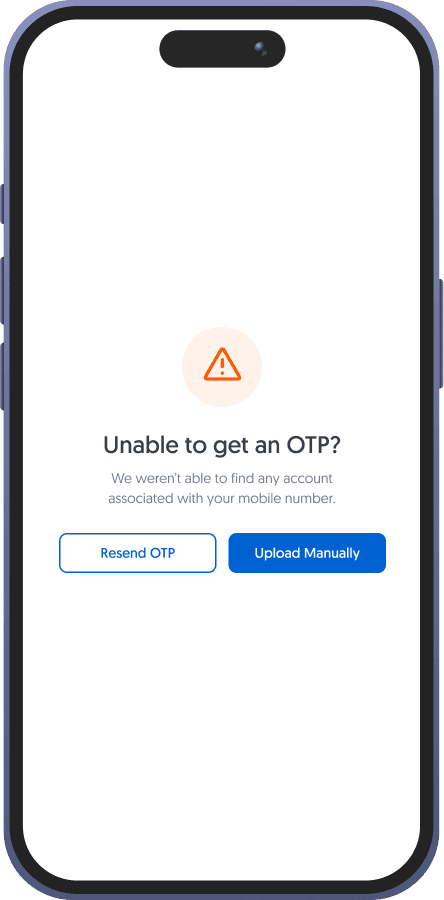
Mitigating journey abandonment by providing a manual document upload path as a secondary service layer during SMS gateway or API failures.
Mitigating journey abandonment by providing a manual document upload path as a secondary service layer during SMS gateway or API failures.
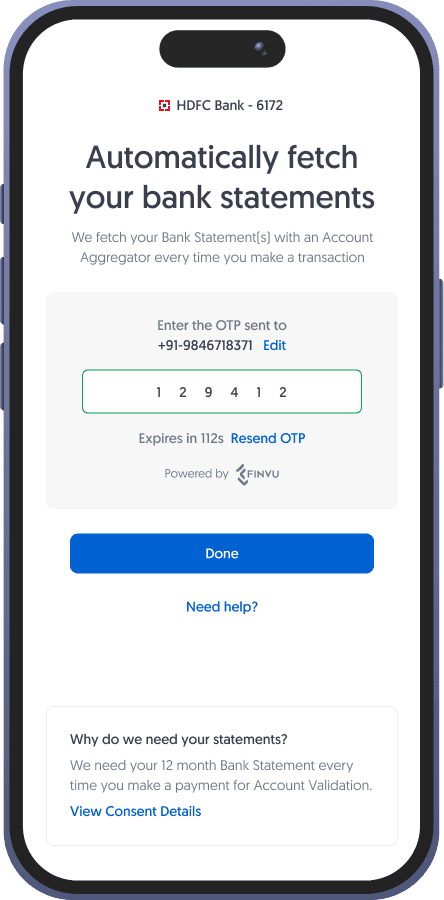
Automating the transition to transaction details only after the system confirms successful identity and account validation.
Automating the transition to transaction details only after the system confirms successful identity and account validation.
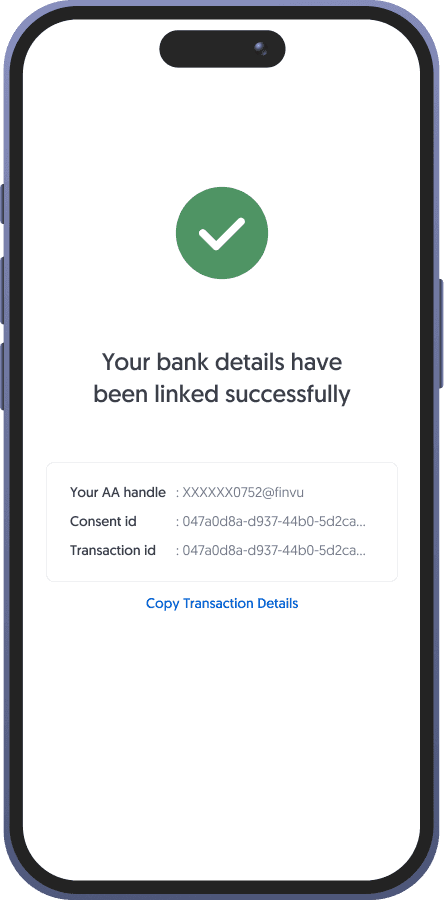
Providing users with unique identifiers (AA Handle, Transaction ID, Consent ID) to ensure a transparent and auditable record of the data handshake before returning to the FIU flow.
Providing users with unique identifiers (AA Handle, Transaction ID, Consent ID) to ensure a transparent and auditable record of the data handshake before returning to the FIU flow.
The Efficiency Milestone
The Efficiency Milestone
By digitizing the consent architecture, we collapsed a 72-hour manual ordeal into a 3-minute digital handshake. This transformation eliminates physical bank visits and administrative fatigue, providing users with instant, secure financial mobility.
By digitizing the consent architecture, we collapsed a 72-hour manual ordeal into a 3-minute digital handshake. This transformation eliminates physical bank visits and administrative fatigue, providing users with instant, secure financial mobility.
Feature
Feature
Feature
Manual Process
Manual Process
Manual Process
AA Flow
AA Flow
AA Flow
Time
Time
Time
~3 Working Days
~3 Working Days
~3 Working Days
<3 Minutes
<3 Minutes
<3 Minutes
Effort
Effort
Effort
Physical visits & PDF management
Physical visits & PDF management
Physical visits & PDF management
One-tap OTP consent
One-tap OTP consent
One-tap OTP consent
Security
Security
Security
Unencrypted data sharing
Unencrypted data sharing
Unencrypted data sharing
End-to-end encryption
End-to-end encryption
End-to-end encryption
I integrated a manual upload fail-safe to prevent journey abandonment during technical outages, ensuring service inclusivity and reliability.
I integrated a manual upload fail-safe to prevent journey abandonment during technical outages, ensuring service inclusivity and reliability.
Credential Alignment & User Agency
Credential Alignment & User Agency
To ensure high success rates, I integrated a real-time credential correction path. This allows users whose banking records are tied to a secondary mobile number to pivot and re-verify without abandoning the entire session.
To ensure high success rates, I integrated a real-time credential correction path. This allows users whose banking records are tied to a secondary mobile number to pivot and re-verify without abandoning the entire session.
Consent Management
Consent Management
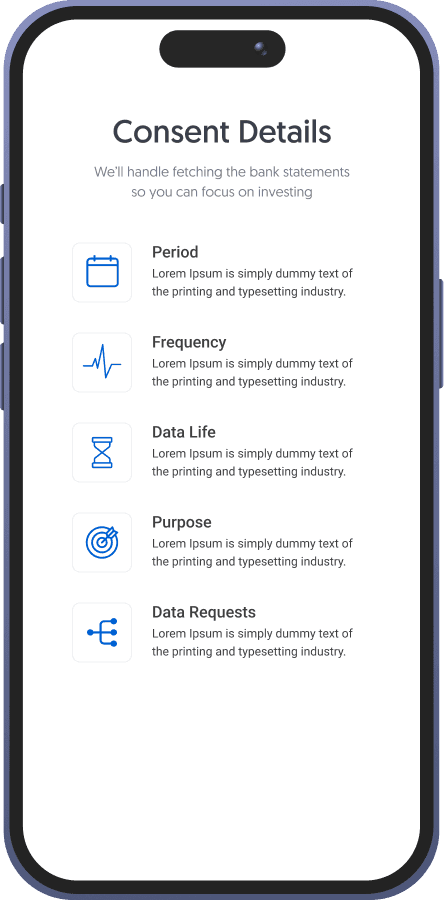
A clear breakdown of what data is being shared, who is receiving it, and how long they can see it.
A clear breakdown of what data is being shared, who is receiving it, and how long they can see it.
Completing the secure link between the FIP and FIU, enabling encrypted real-time data sharing under the user's explicit authorization.
Completing the secure link between the FIP and FIU, enabling encrypted real-time data sharing under the user's explicit authorization.
The consent dashboard
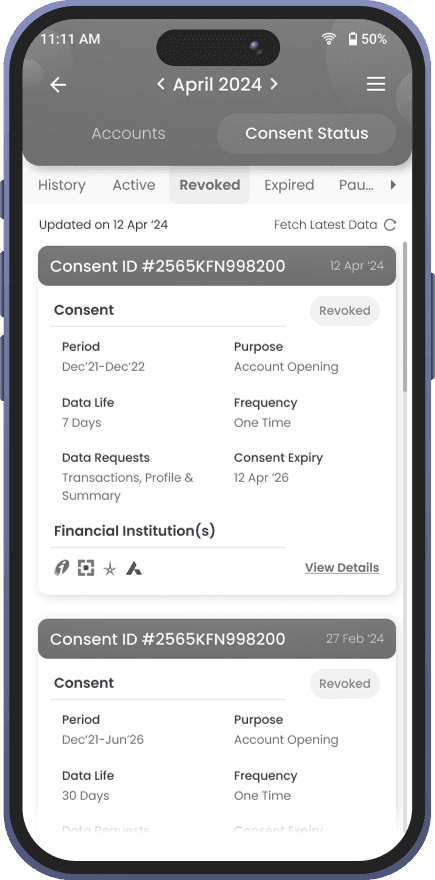
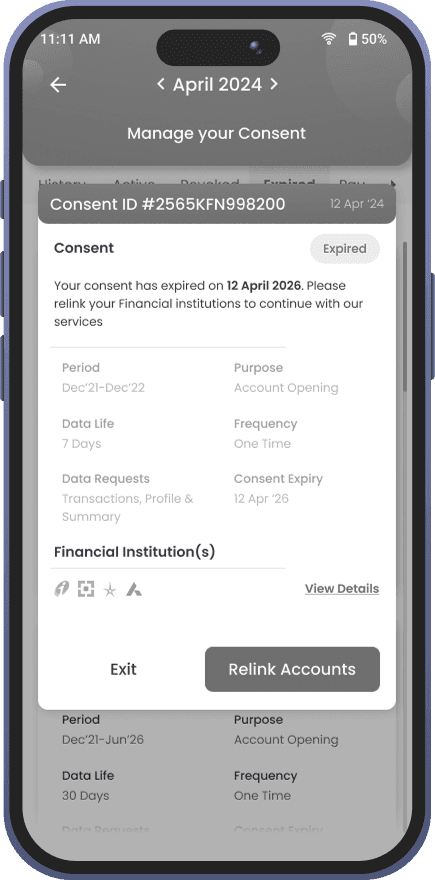
Every consent in one place: active, paused, revoked, expired.
Every consent in one place: active, paused, revoked, expired.
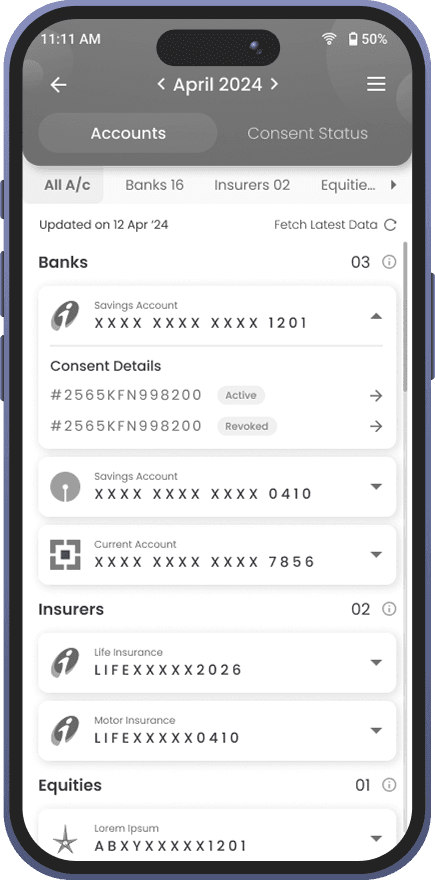
A centralized hub providing a transparent overview of all linked accounts and their associated consent statuses, putting data control back in the user's hands.
A granular history view that maps every Consent ID to its specific parameters and financial institutions, providing a full audit trail for total data transparency.
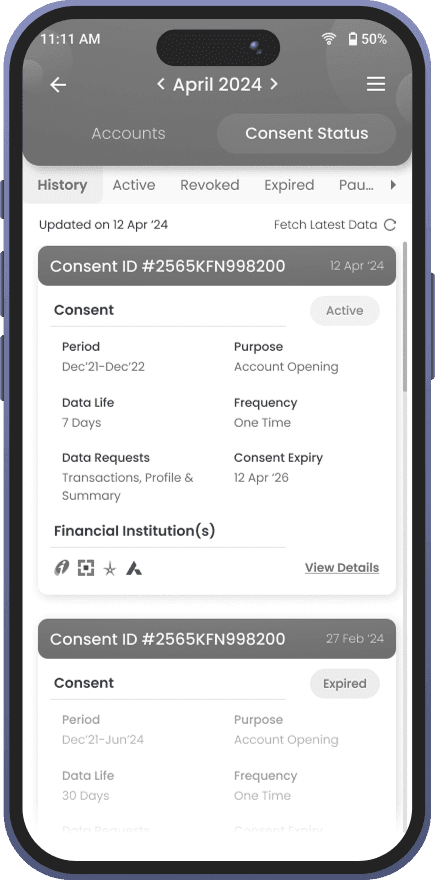
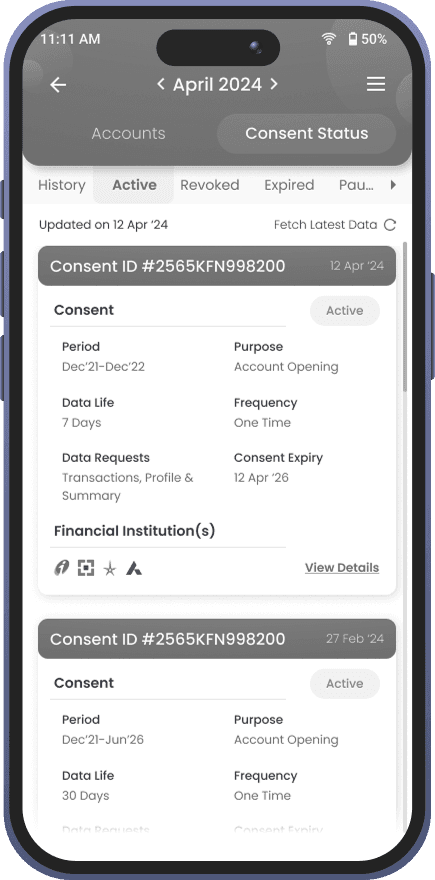
A chronologically organized view of active consents that highlights the last update, ensuring users can monitor and manage their current data sharing at a glance.
A chronological audit trail of all revoked consents, allowing users to track their historical privacy decisions and maintain a record of terminated data access.
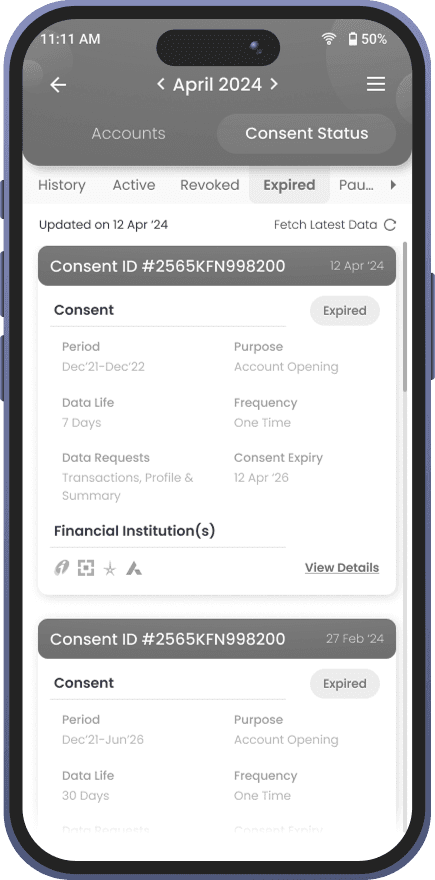
A dedicated list for consents past their tenure, empowering users to either maintain a record of expired access or seamlessly relink accounts for a new period.
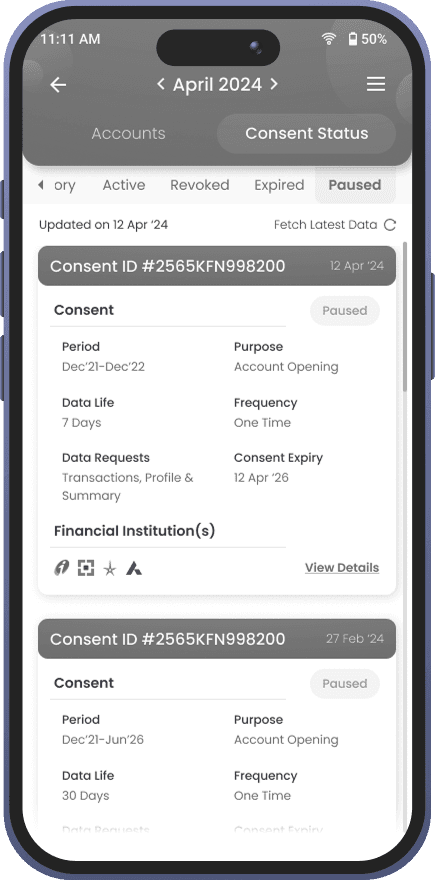
A centralized list of paused consents accompanied by contextual impact warnings, ensuring users understand the consequences of halting data flow before confirming.
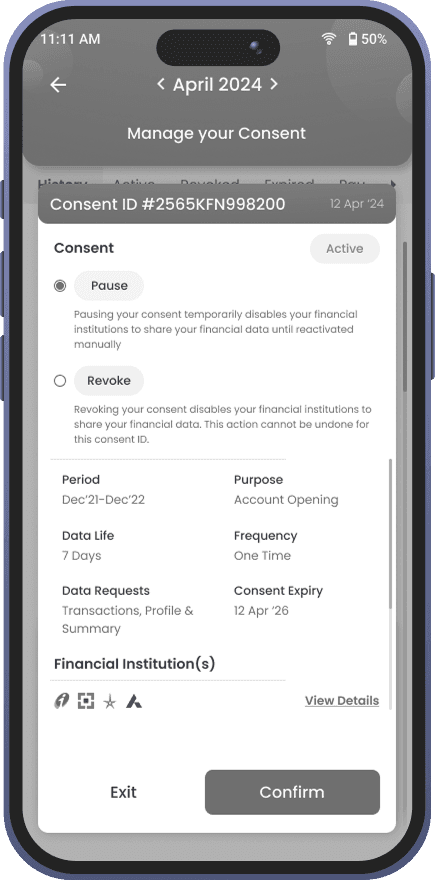
Prathamesh, a month later: policy approved, he opens the dashboard and revokes the insurer's access.
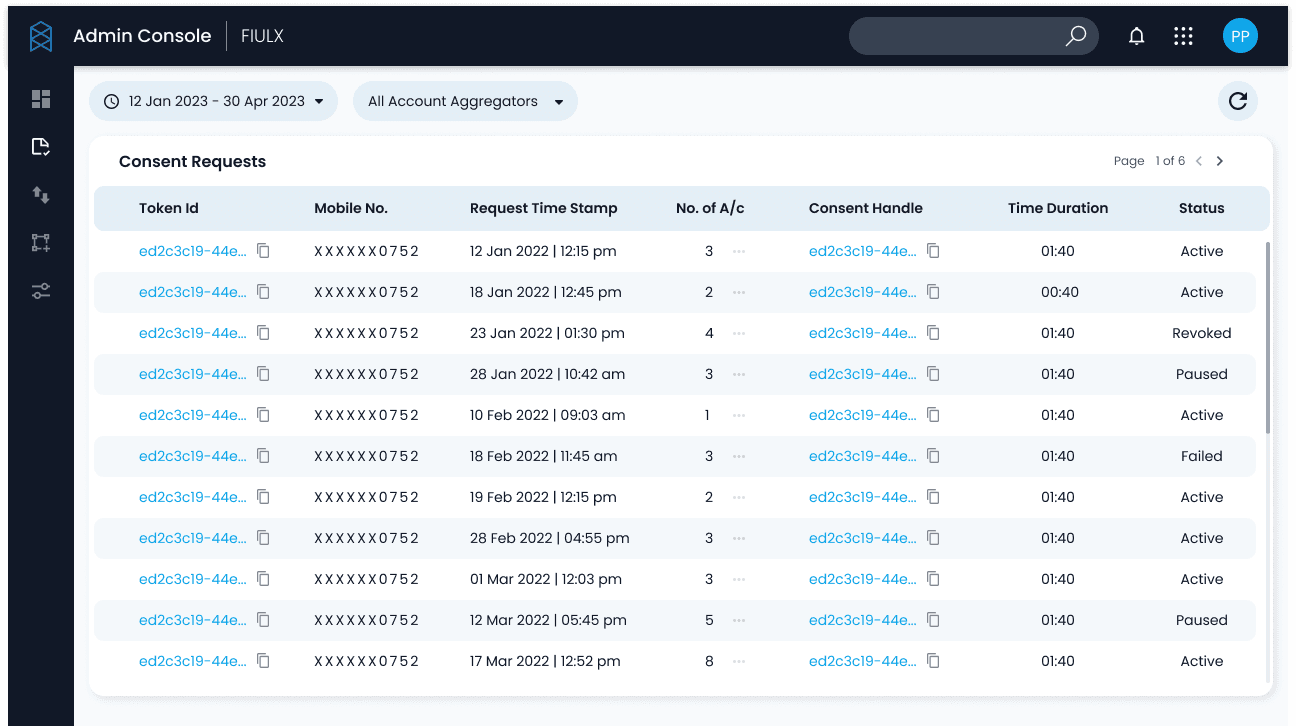
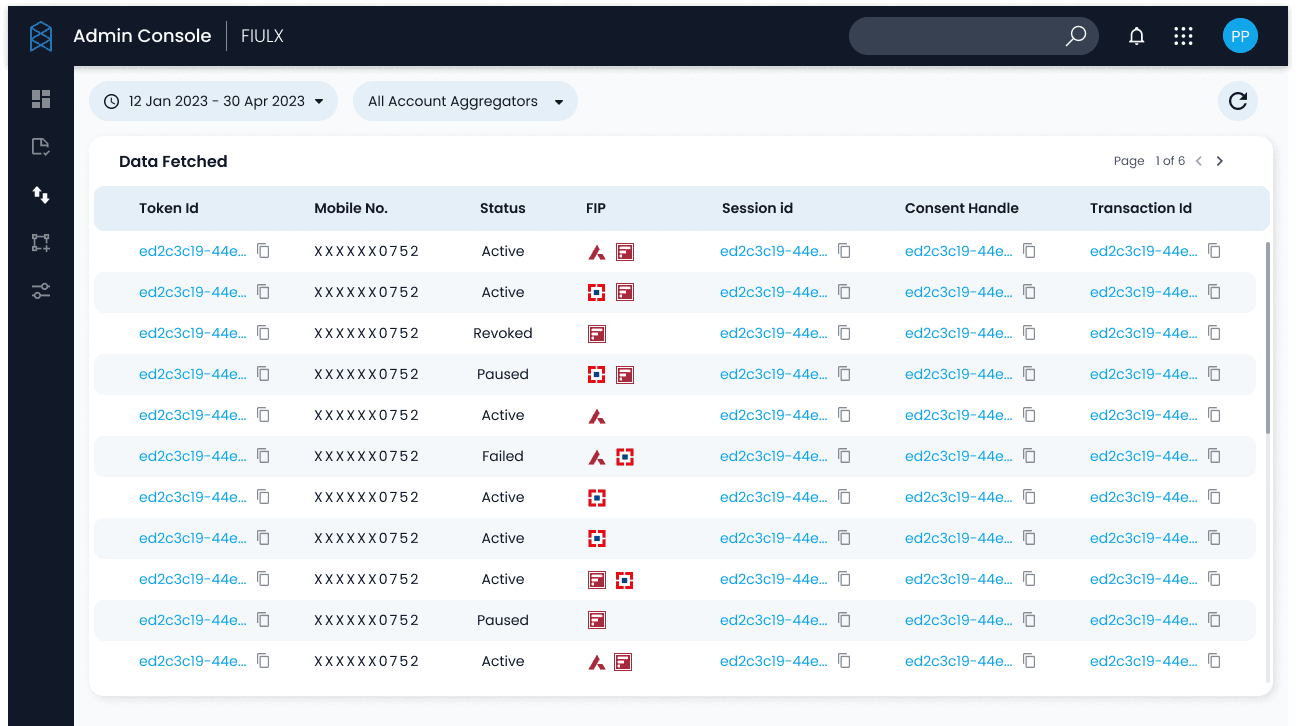
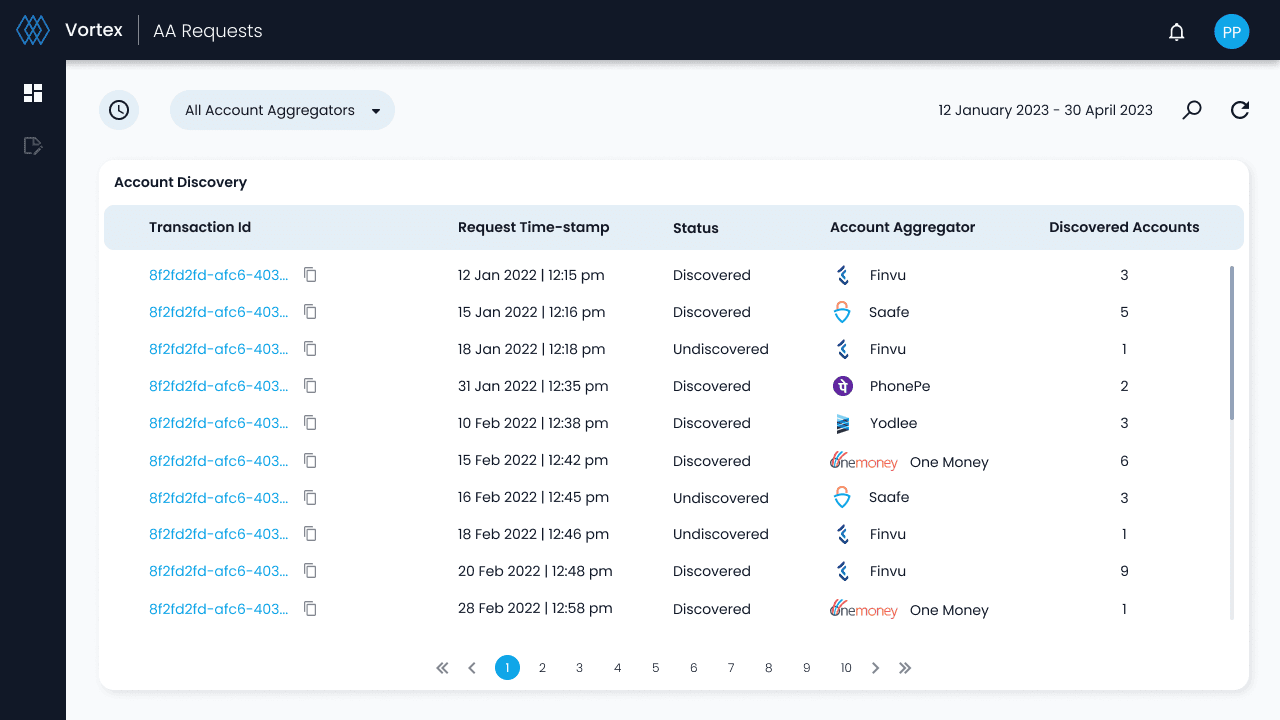
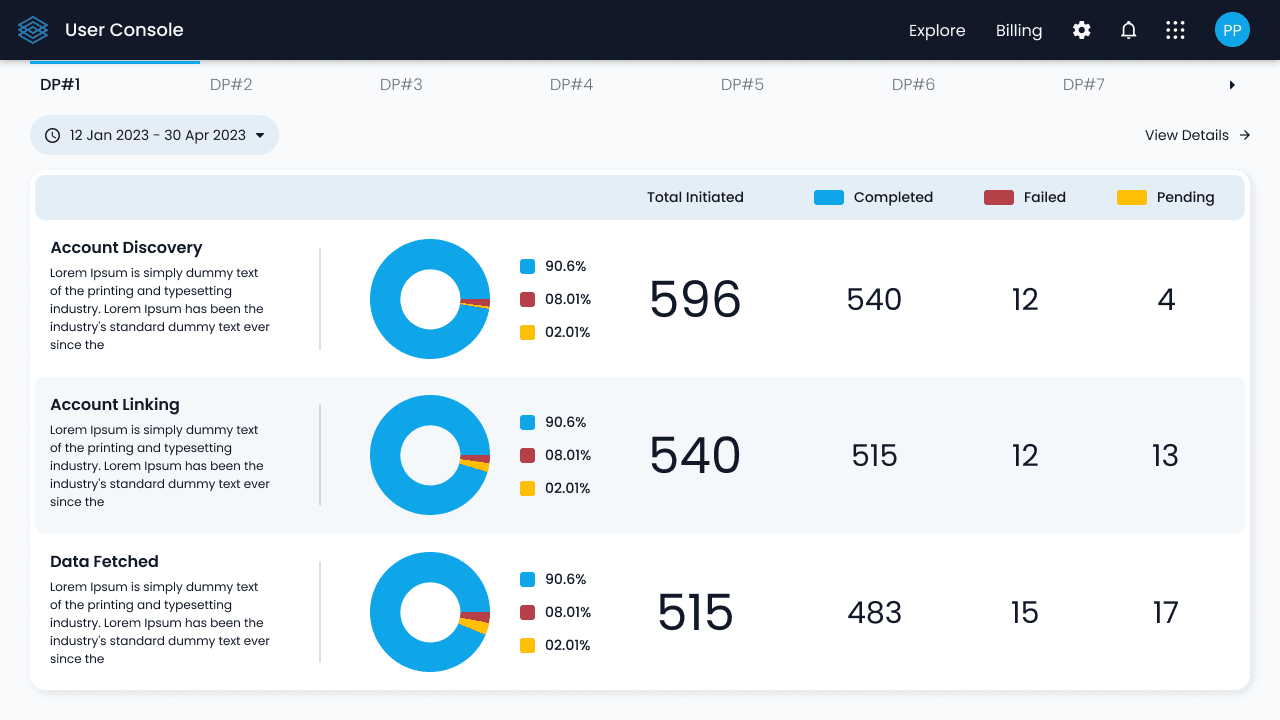
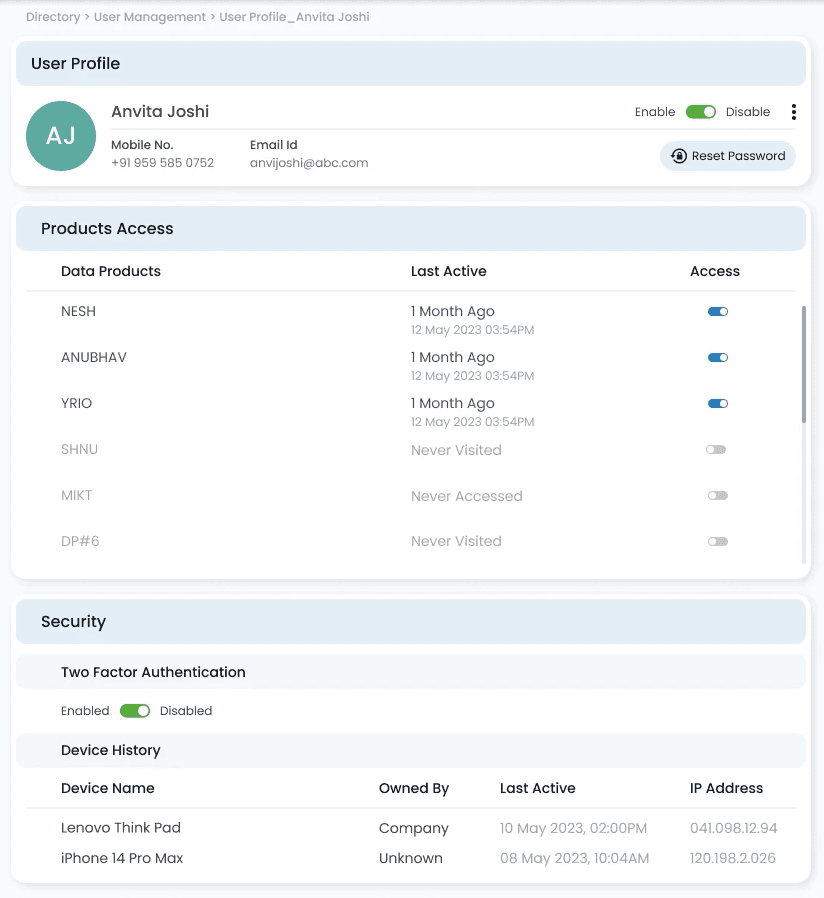
Admin consoles
Oversight for banks, lenders, and clients. Curated to respect partner confidentiality.
FIU Admin Console
FIP Admin Console
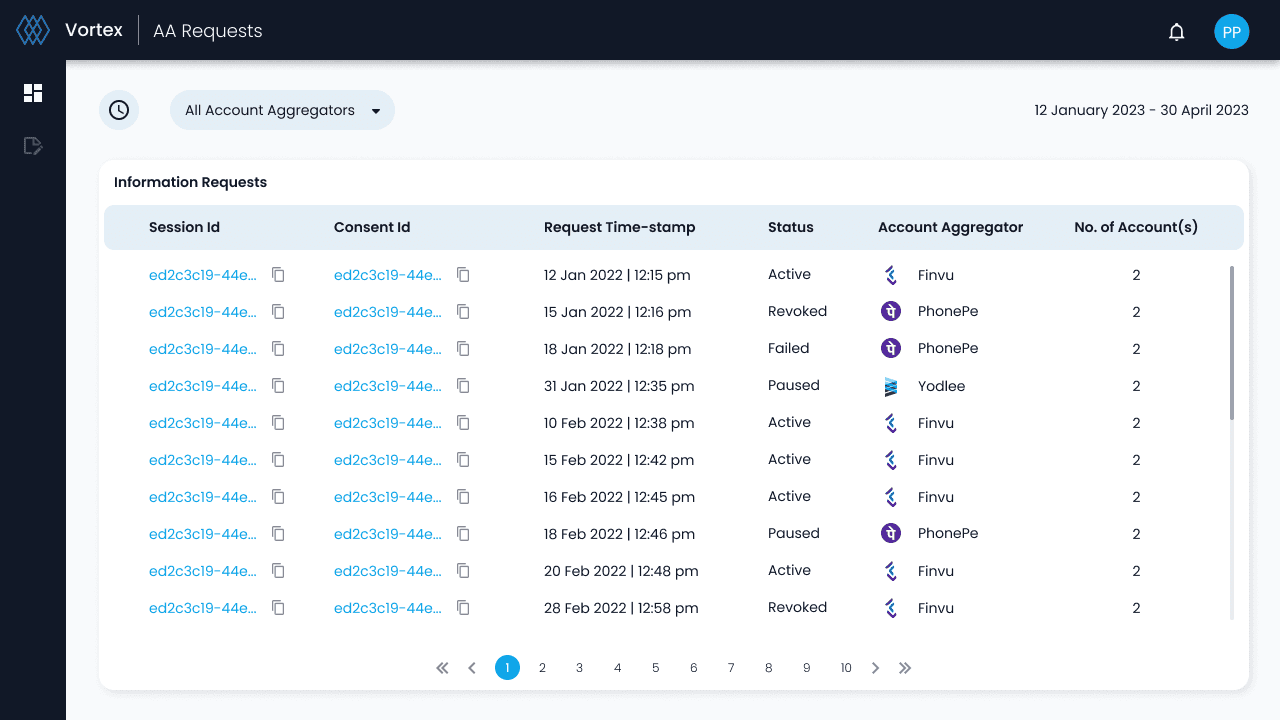
Client Console
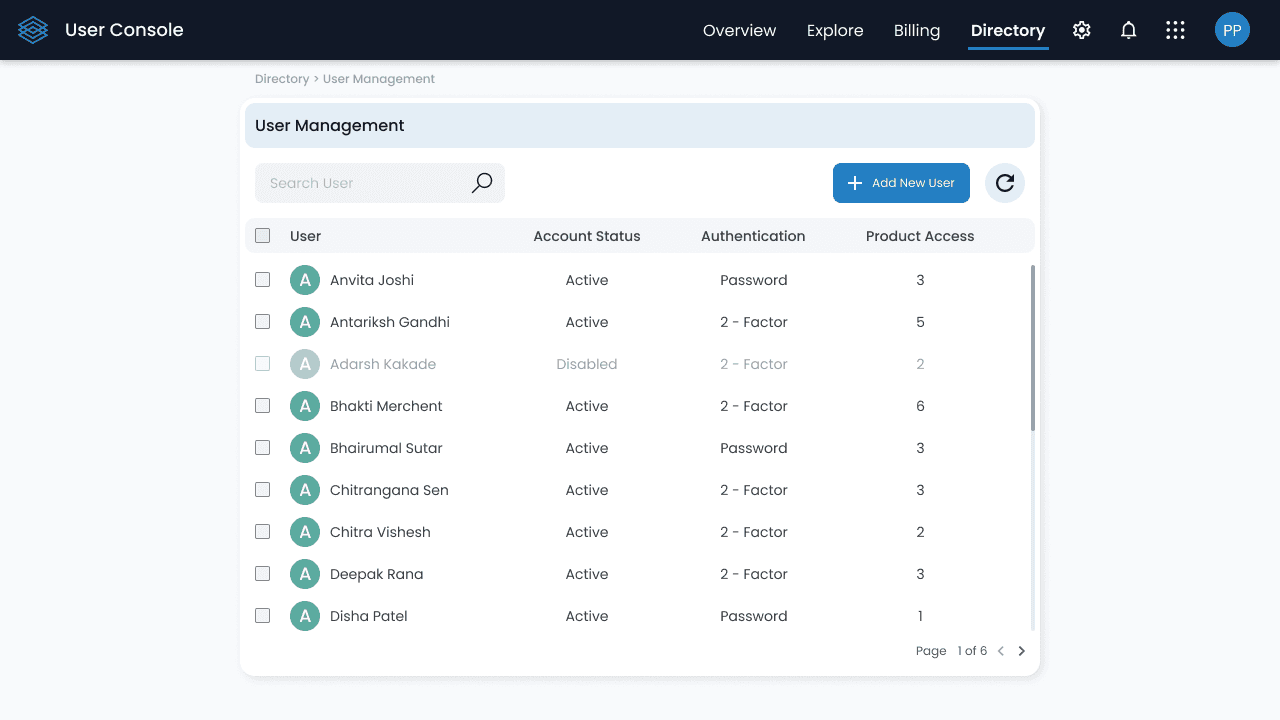
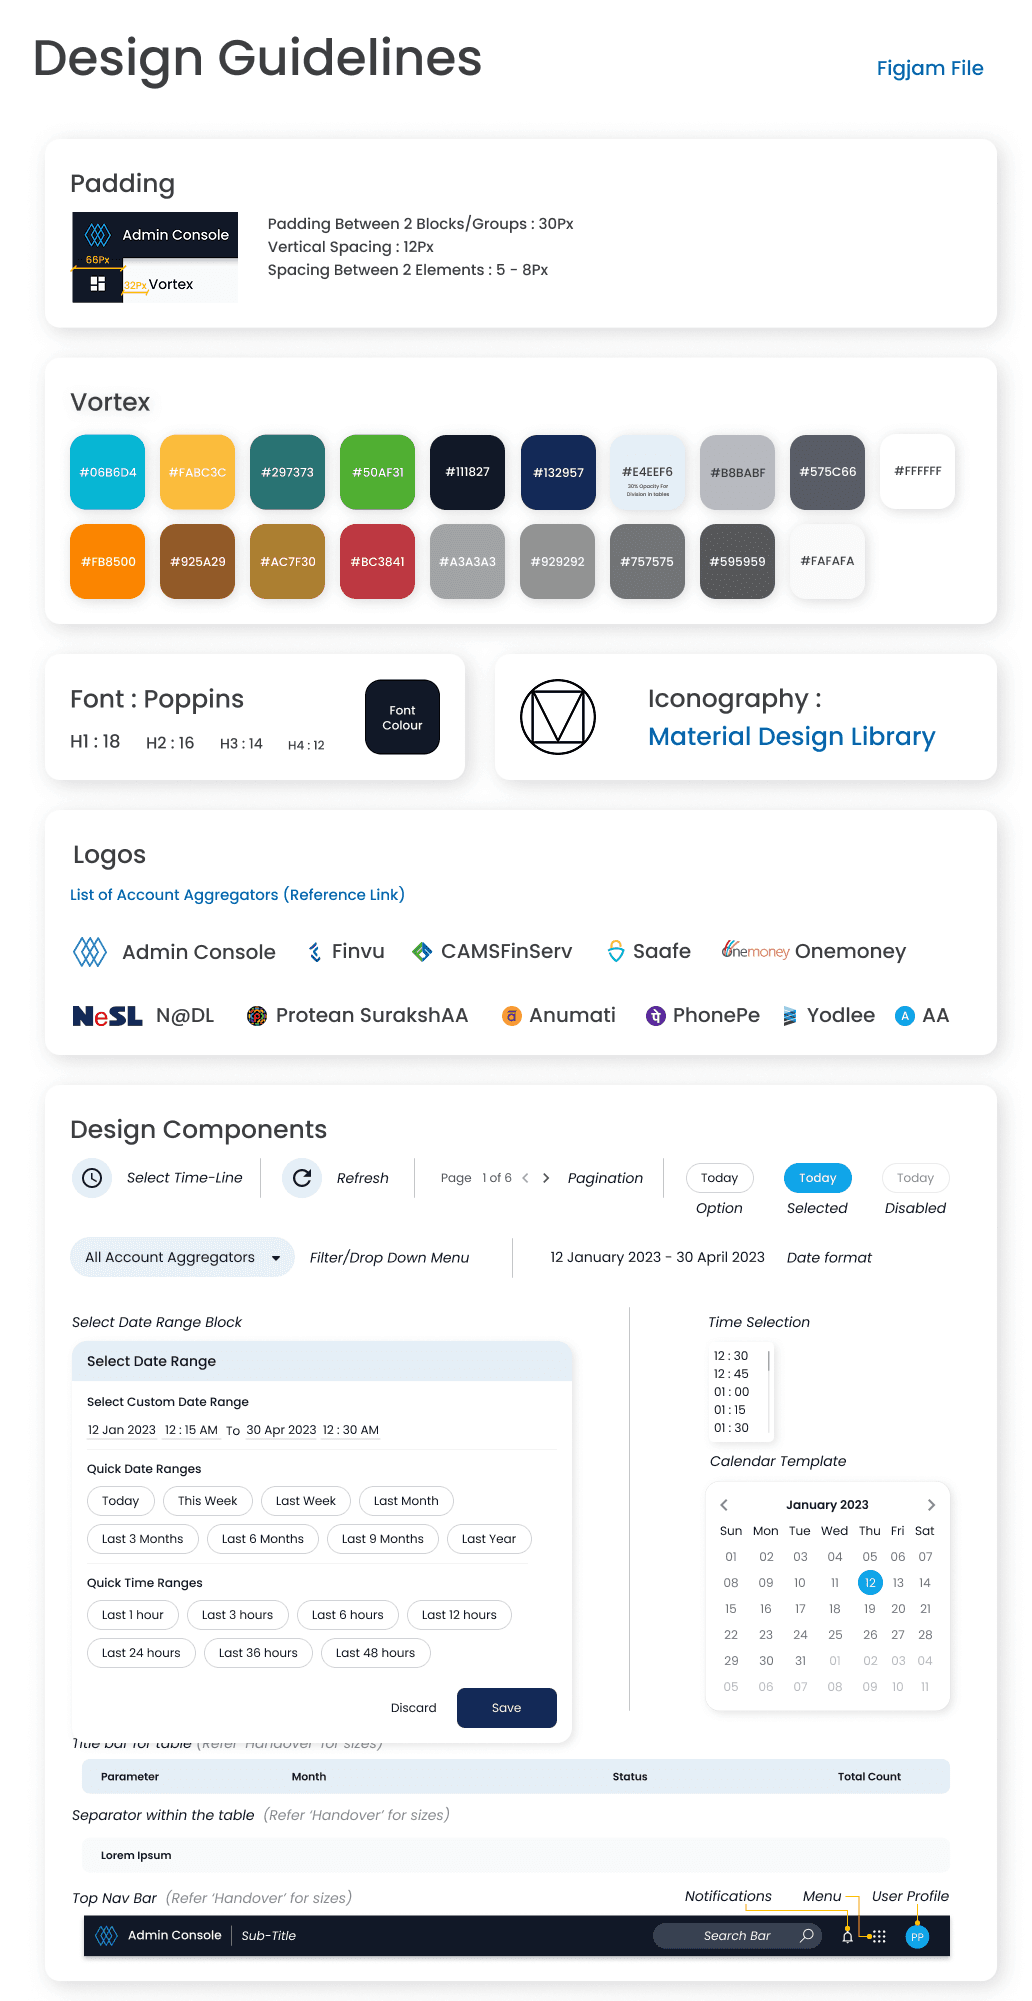
Design standards
One style guide across every surface.
Impact
Impact
40% → 5%
Across three rounds of redesign, people went from abandoning the journey to finishing it.
Across three rounds of redesign, people went from abandoning the journey to finishing it.
What Transfers
What Transfers
The same principles apply anywhere people share sensitive data between institutions, from open banking to health data exchange:
The same principles apply anywhere people share sensitive data between institutions, from open banking to health data exchange:
01
Transparency is the best onboarding.
Transparency is the best onboarding.
02
Fewer blind decisions beat fewer steps.
Fewer blind decisions beat fewer steps.
03
Design the failure, not just the flow.
Design the failure, not just the flow.
Reflection
Reflection
Beyond the interface
A front-stage screen only works when the back stage is designed too.
A front-stage screen only works when the back stage is designed too.
Next time:
I'd track drop-off at every step, for every phase, so it's clear which change did the most work.
I'd track drop-off at every step, for every phase, so it's clear which change did the most work.